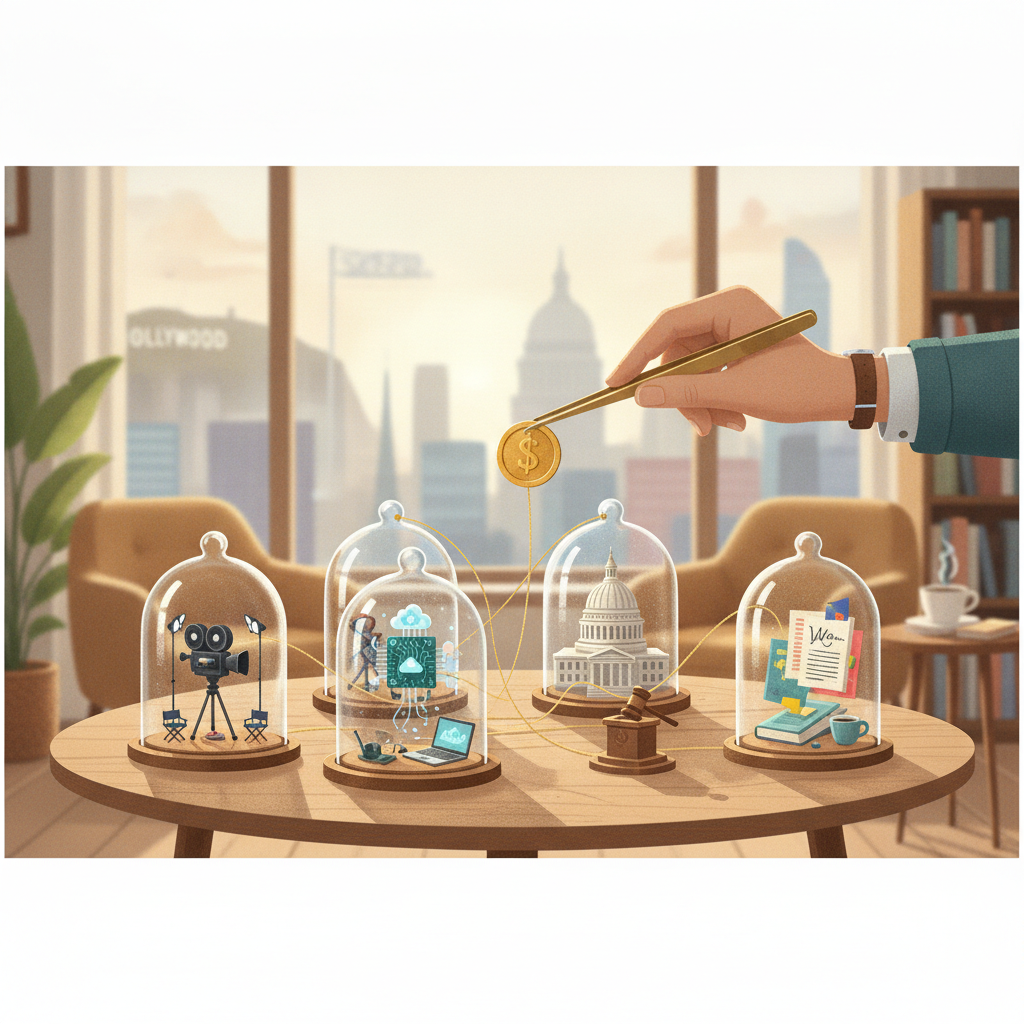
A valuation near $250 million buys control of Puck this week. RedBird Capital is the buyer, the existing institutional investors are the sellers, and the company changing hands is a five-year-old digital outfit with a tiny staff and a roster of named journalists who cover four rooms: Silicon Valley, Hollywood, Washington, and Wall Street. Nothing about that description sounds like a quarter-billion-dollar asset by the standards the industry spent fifteen years internalizing, which is exactly why the price RedBird is willing to pay for control is worth sitting with.
Most of the trade assumed scale was the only path available. Grow the audience, dilute the voice, sell the impressions, chase the feed wherever the feed happened to be that quarter. Puck did the inverse of every one of those moves. It hired a small number of named writers with real access, and it charged readers directly for what those writers knew. No programmatic flood. No pivot to video. No race to the bottom of the funnel in search of volume that never paid for itself. The company that refused the funnel is now worth a quarter billion to an investor whose portfolio otherwise lives in sports and entertainment.
What RedBird Is Actually Buying at $250 Million
Look at what is being purchased, because it is not the thing the headline implies. It is not an audience. Audiences are free to assemble and equally free to leave, and anyone who has watched a platform algorithm change overnight knows how quickly an audience can stop being an asset. What RedBird is paying for is a set of relationships that took years to earn and cannot be reconstructed from a spreadsheet, a hiring plan, or a budget. A journalist who can get a Hollywood lawyer on the phone is not a line item on a staffing model. That person is a moat, and moats are the thing private capital has always paid premiums for, in media or anywhere else.
The distinction matters because it explains the price. Reach can be bought at auction, and its cost is well known and falling. Access cannot be bought at auction at all. It accrues to specific people over years of being useful, discreet, and accurate, and it evaporates if any of those conditions break. An asset that cannot be manufactured on demand gets priced on scarcity rather than on cost, and scarcity pricing looks irrational right up until you ask what it would take to build the same thing from scratch.
Generic Media Is Dying, Specific Media Is Not
This is the part the loudest version of the story keeps missing. Everyone wants to talk about media dying, and there is plenty of evidence to quote in support. Media is not dying. Generic media is dying, and it is dying because generic is precisely what the machine now produces at zero marginal cost. The specific kind, built on trust between a writer, a source, and a reader who actually cares what that writer found out, keeps finding buyers. Puck is the proof of that, priced at $250 million and sold to someone who does this for a living.
The instinct to go narrow and deep runs against every incentive the modern web hands you. Widen. Optimize. Distribute. The machine measures reach and reports it back as progress, and the number goes up, and the meeting goes well. But reach without a reason to return is just noise with a chart attached. The durable thing is the person on the other side deciding, again and again, without being nudged, that this was worth their attention. That decision is the only real inventory a publication has, and it does not show up in the dashboard that everyone optimizes.
I keep coming back to the shape of that idea in places far from media. A sumo wrestler who tells good stories is remembered for the stories, not for the weight class. A bird builds its nest in one of a thousand acceptable ways, and the particular way is not an inefficiency to be optimized away but the thing that makes it a nest rather than a diagram. A rule only starts to matter once there is something real being traded under it. The thread running through all of them is the same: what is real is the particular, and the particular is what survives when the generic washes out. We are told there is one right way to build, one right way to scale, one right way to win the feed. There never was, and the exits keep confirming it.
Why Scarcity Sets the Price, Not Headcount
There is a quieter lesson sitting in plain sight about how people lose what they built. The common read blames money, fame, or the other party in the room. The truer read is smaller and less satisfying. What lets someone get taken is rarely their wealth; it is their availability, the plain fact of being present and unguarded in front of anyone who wants something. The same holds for a media brand. The asset that gets drained is the attention and trust handed out free in exchange for reach, not the pile of cash that observers assume caused the fall. Spend the trust widely enough and there is nothing left to sell, regardless of how large the audience number got.
The training for holding onto any of it is not dramatic, which is why so few organizations do it. It happens on the dull walk, the repeated street, the ordinary Tuesday when nobody is watching and nothing is at stake. You practice attention in the boring places or you simply do not have it available when it counts. A brand, a portfolio, and a relationship all compound out of unglamorous repetitions nobody photographs, and the compounding is invisible until the moment someone tries to buy the result.
Markets price this correctly even when the commentary does not. RedBird is not a media company and has no particular interest in being one. It is a roll-up investor that understands scarcity as a category, and it is paying for the one thing the internet has made rarer every single year: a trusted human voice with a direct line to power, plus readers willing to pay for that line. That is why a five-person newsroom can beat a thousand-person one on price. Scarcity sets the number. Headcount never did.
The Narrow Road Stays Valuable
The comfortable take is that Puck sold out, that the exit reveals what the project was really about all along. The sharper read is that the exit proved the opposite of the consensus it was built against. You can make something worth a fortune by refusing the fortune-seeking behavior everyone else copied, and the sale is the evidence for that claim rather than a betrayal of it. A price is the most legible argument available, and this one argues against the funnel.
We spend enormous energy widening things that did not need widening, because widening is legible, fundable, and easy to describe in a meeting. The edge was never the scale. It was the specific thing only you could build, the relationship only you earned, and the attention you decided to keep rather than spend on reach that would not return. Puck held that line for five years and got paid for holding it. Most will still chase the funnel, and that is precisely why the narrow road stays valuable.
Leave a Reply